Sea-level rise becomes an inequality issue when flood exposure, financial capacity, and decision-making power are unevenly distributed. Households with fewer resources, renters, and people who depend on disrupted public services can carry serious costs even when they do not own waterfront property.
A flood-risk assessment, insurance review, or climate-resilience planning service can clarify choices, but it cannot guarantee future coverage, property values, or protection.
The most useful decisions compare who pays, who benefits, and who could be displaced—not only how well a project reduces water damage. Local conditions, program rules, and the timing of future flooding must always be checked locally.
At a Glance
- Sea-level rise affects people unequally because exposure and the ability to recover from flooding are not shared equally.
- Adaptation is not automatically fair: seawalls, drainage, home elevation, and relocation can shift costs or displacement risks between groups.
- A good coastal plan looks beyond property loss to housing stability, insurance pressure, transport, healthcare, schools, and community voice.
| Response | Who May Pay | Main Protection Value | Key Equity Trade-Off |
|---|---|---|---|
| Seawalls and barriers | Often public budgets, property owners, or both | Can reduce direct coastal exposure for protected areas | Benefits may concentrate around selected assets while maintenance obligations continue |
| Home elevation and floodproofing | Usually individual owners, sometimes with public support | Can reduce damage to a specific building | May be out of reach for lower-income owners and does not directly protect renters |
| Drainage, wetlands, and public infrastructure | Municipal budgets and infrastructure programs | Can support broader neighborhood resilience | Access and benefits can remain uneven if vulnerable areas are not prioritized |
| Buyouts and relocation support | Public programs, households, and receiving communities | Can reduce long-term exposure by moving people or assets | Housing supply, voluntary choice, and community stability are central concerns |
Why Rising Seas Create Unequal Risks
Rising seas can increase the frequency and severity of coastal flooding, including high-tide flooding in low-lying areas. The damage is not limited to a flooded building. It can affect the ability to get to work, reach healthcare, attend school, operate a small business, or receive emergency support.
The Three Drivers: Exposure, Financial Capacity, and Political Voice
Exposure asks who lives, works, or depends on services in areas facing coastal flooding. Financial capacity asks who can repair damage, relocate, elevate a home, handle insurance costs, or pause business operations. Political voice asks whose needs are represented when a city chooses where to invest in drainage, roads, barriers, or relocation programs.
A household may have high exposure but little ability to move. Another may have lower direct exposure but still suffer when nearby roads, water systems, transit, or healthcare services are disrupted. This is why a resilience plan should examine people as well as parcels.
Why Flood Maps Alone Do Not Show the Full Social Impact
A flood map can be a valuable part of a flood-risk assessment, but it does not show every social consequence. It may not capture whether residents are renters, whether a neighborhood has accessible transport during an emergency, or whether a local school and clinic can remain usable after flooding.
Property-loss estimates also do not fully show displacement pressure. A renter may lose housing after flood damage or redevelopment without ever appearing as the owner of an affected property. Community-led planning can help identify these vulnerabilities before a project is selected.
Three-Line Summary: Who Is Most Likely to Bear the Cost
Lower-income households may have fewer resources to repair, relocate, elevate homes, or absorb insurance costs. Renters may face displacement despite not owning the flooded property. Communities that rely on fragile public infrastructure may carry indirect costs long after water recedes.
Compare Coastal Responses by Cost, Protection, and Fairness
There is no single best coastal adaptation option. The practical comparison is not simply “which project stops water?” It is who pays upfront, who handles ongoing costs, who gains protection, and who could be left with a new burden.
Seawalls and Barriers: Protection Benefits, Maintenance Obligations, and Spillover Risks
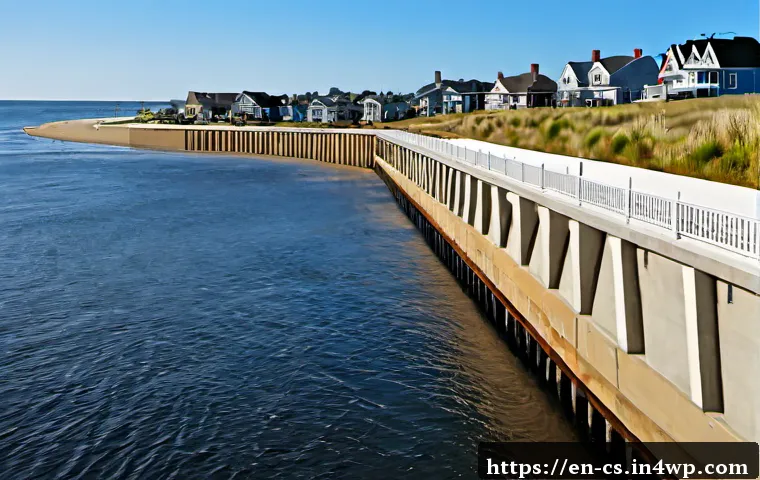
Seawalls and barriers may protect selected coastal locations from direct water exposure. They also create ongoing maintenance obligations, and their benefits may be concentrated around particular properties, roads, or commercial areas. A planning process should ask whether nearby areas receive comparable attention or face additional risk.
Before backing a barrier project, ask for a clear description of the protected area, maintenance responsibility, public-service access, and how the plan considers affordable housing and transit connections.
Home Elevation and Floodproofing: When Household-Level Upgrades Are Realistic
Home elevation and floodproofing focus on individual buildings. They may be relevant for some owners, but they require resources, property-specific decisions, and realistic expectations about what they can protect. They may not be feasible for every household, and renters generally do not control these investments.
A property owner considering upgrades should review the building’s conditions, insurance terms, likely disruption during work, and whether the investment aligns with a wider local adaptation plan. Do not assume an upgrade guarantees future insurability or eliminates flood risk.
Drainage, Wetlands, and Public Infrastructure: Shared Protection Versus Uneven Access
Drainage upgrades, wetlands, roads, water systems, and emergency-response capacity can provide shared benefits. They matter because flooding can interrupt everyday services even for people whose homes are not directly damaged. Yet a public investment can still be unequal if it overlooks neighborhoods with aging infrastructure or limited political influence.
An equitable infrastructure proposal identifies which communities receive the benefit, which services remain vulnerable, and whether residents can access the planning process in practical ways.
Buyouts and Relocation: Voluntary Choice, Housing Supply, and Long-Term Stability
Buyouts and relocation support can reduce long-term exposure, but their fairness depends on voluntary choice, clear eligibility rules, available housing, and long-term stability for households that move. A relocation option is not meaningful if it separates residents from jobs, schools, healthcare, or social support without viable alternatives.
Programs should be reviewed carefully because local funding, eligibility, and timelines can vary. The key question is not only whether relocation is offered, but whether people can make a stable choice without being pushed into worse housing conditions.
Where Inequality Shows Up in Housing, Insurance, and Public Services
Homeowners, Renters, and Landlords Face Different Incentives and Losses
Homeowners may face repair decisions, property-value uncertainty, mortgage questions, and insurance pressure. Renters may experience damaged housing, lease disruption, rent increases, or displacement after redevelopment. Landlords may decide whether to repair, sell, upgrade, or change the use of a property.
For this reason, a coastal resilience strategy needs tenant protections and housing stability questions, not only owner-focused property measures. Treating every affected household as an owner leaves a large part of the risk unseen.
Insurance Affordability, Deductibles, Exclusions, and Coverage Gaps
Flood insurance can be an important part of risk management, but it is not a complete answer to sea-level-rise risk. Affordability, deductibles, exclusions, coverage limits, and changing terms can affect whether a policy is useful after a flood.
When reviewing insurance, ask what events and losses are covered, what the deductible means in practice, and what documentation may be needed after damage. Future premiums and coverage availability cannot be assumed. For a property portfolio, an insurance review should be considered alongside a current flood-risk assessment and continuity planning.
Schools, Roads, Healthcare, and Utilities as Hidden Sources of Unequal Burden
Coastal flooding can disrupt transport, healthcare, schools, water systems, and emergency response. These disruptions often place a heavier burden on people who cannot easily work remotely, travel farther, arrange alternative care, or absorb interruptions to income.
A plan that protects expensive buildings but leaves access roads, clinics, or water systems exposed may reduce visible property losses while preserving unequal hardship. Service continuity is a core equity measure.
Practical Steps for Households, Businesses, and Local Decision-Makers
Questions to Ask Before Paying for a Flood-Risk Assessment or Property Upgrade
- What local data and assumptions are being used?
- Does the assessment address building risk, access routes, and critical services?
- What costs are immediate, and what maintenance or follow-up costs may remain?
- How could insurance terms, mortgages, or property decisions be affected?
- Who is not represented in the analysis: renters, small businesses, older residents, or people with mobility needs?
A useful provider explains the scope clearly. It should distinguish known conditions from uncertain future outcomes rather than presenting a single prediction as guaranteed.
Building a Household or Business Continuity Plan Without Assuming Guaranteed Protection
A continuity plan can identify important documents, communication needs, access routes, service dependencies, and steps to take after disruption. For a small business, it may include supplier access, employee communication, equipment protection, and alternatives if roads or utilities are interrupted.
Keep the plan practical. A seawall, drainage project, insurance policy, or building upgrade may reduce some risks, but none should be treated as a promise that flooding or disruption will not occur.
What Equitable Community Engagement Should Include
Equitable engagement means more than announcing a finished project. Residents, renters, business owners, service users, and community organizations should have a meaningful chance to identify problems and compare choices. The process should make room for concerns that property-loss models may overlook, including displacement, access to healthcare, transit, schools, and emergency support.
Situations That Need Different Solutions
Low-Income Coastal Neighborhoods With Aging Infrastructure
These areas may need attention to drainage, transport, water systems, emergency access, and housing stability at the same time. A household-only approach can be too narrow when public services are already vulnerable.
Rental-Heavy Districts Facing Redevelopment Pressure
Flooding or adaptation investment can be followed by redevelopment pressure. Decision-makers should examine whether renters can remain safely housed, whether landlords have incentives to repair, and whether protective measures are paired with practical tenant safeguards.
Small Coastal Businesses Dependent on Tourism, Ports, or Local Access
Small businesses can be affected by flooded access roads, disrupted utilities, reduced customer access, and operational interruptions. A business continuity plan and local resilience planning process should consider access and recovery needs, not just building-level water exposure.
Communities Considering Relocation Versus Long-Term Defensive Infrastructure
This decision requires a long view. Defensive infrastructure may protect some locations but requires maintenance and may distribute benefits unevenly. Relocation may lower exposure but raises questions about choice, housing supply, public services, and preserving community connections.
Choosing an Adaptation Path: Decision Criteria and Comparison Summary
Compare Who Pays, Who Benefits, Who Remains Protected, and Who May Be Displaced
Use a simple comparison before selecting a project: identify the cost bearer, the protected group, the people outside the protected area, and the possible effects on renters and public services. This approach makes it harder to label a project “resilient” when it simply transfers risk elsewhere.
Selecting Flood-Risk, Insurance, Engineering, or Resilience-Planning Support
When choosing a flood-risk assessment, property insurance adviser, engineering firm, or climate-resilience consulting partner, look for local data, clear scope, community engagement experience, insurance awareness, and transparent pricing. Ask whether the work addresses housing and service disruption alongside physical flood exposure.
Check the provider’s official information page for the exact scope of work, exclusions, local coverage, and pricing conditions before making a commitment.
A Final Checklist for Transparent, Fairer Coastal Decisions
- Does the proposal state who pays for construction, maintenance, repair, or relocation?
- Does it explain who benefits, including renters and users of public services?
- Does it identify possible displacement or redevelopment pressure?
- Does it account for roads, schools, healthcare, water, and emergency response?
- Does it separate verified local information from uncertain future projections?
Closing Thoughts
Sea-level rise is a physical hazard, but its consequences are shaped by housing, income, insurance, public infrastructure, and political choice. A project can reduce flood exposure while still creating unfair costs if it overlooks renters, service access, or displacement. Better coastal decisions start by comparing social impacts as carefully as engineering performance. The goal is not to promise certainty, but to make trade-offs visible before they become irreversible.
Useful Things to Know
Property risk is not the same as household risk. A home may avoid direct damage while its residents still lose access to roads, schools, healthcare, utilities, or work.
Insurance is one layer of preparation. Review policy terms carefully and do not assume future premiums, coverage, or eligibility will remain unchanged.
Community input can reveal overlooked risks. Residents often know which routes, services, and housing pressures are most important during flooding.
Important Considerations
The timing, extent, and severity of flooding vary by location and require local review. Future insurance premiums, property values, mortgage availability, and public-program eligibility cannot be predicted with certainty. No individual adaptation project can be assumed to prevent displacement or distribute benefits fairly without a transparent local evaluation.
Frequently Asked Questions
Q1. Why does sea-level rise affect low-income communities more severely?
A1. Lower-income households often have fewer financial resources to repair flood damage, relocate, elevate homes, or manage rising insurance costs. They may also rely more heavily on public transport, schools, healthcare, and utilities that coastal flooding can disrupt.
Q2. Is flood insurance enough to protect a household from sea-level-rise risk?
A2. No. Insurance may help with certain covered losses, but affordability, deductibles, exclusions, and coverage gaps matter. It also does not necessarily address displacement, service interruptions, changing property conditions, or future coverage availability.
Q3. Which coastal adaptation option is most affordable for a community?
A3. There is no universal answer. Affordability depends on who pays upfront, ongoing maintenance needs, the level of protection provided, effects on public services, and whether the option creates displacement pressure. Comparing these factors openly is more useful than judging a project by engineering performance alone.